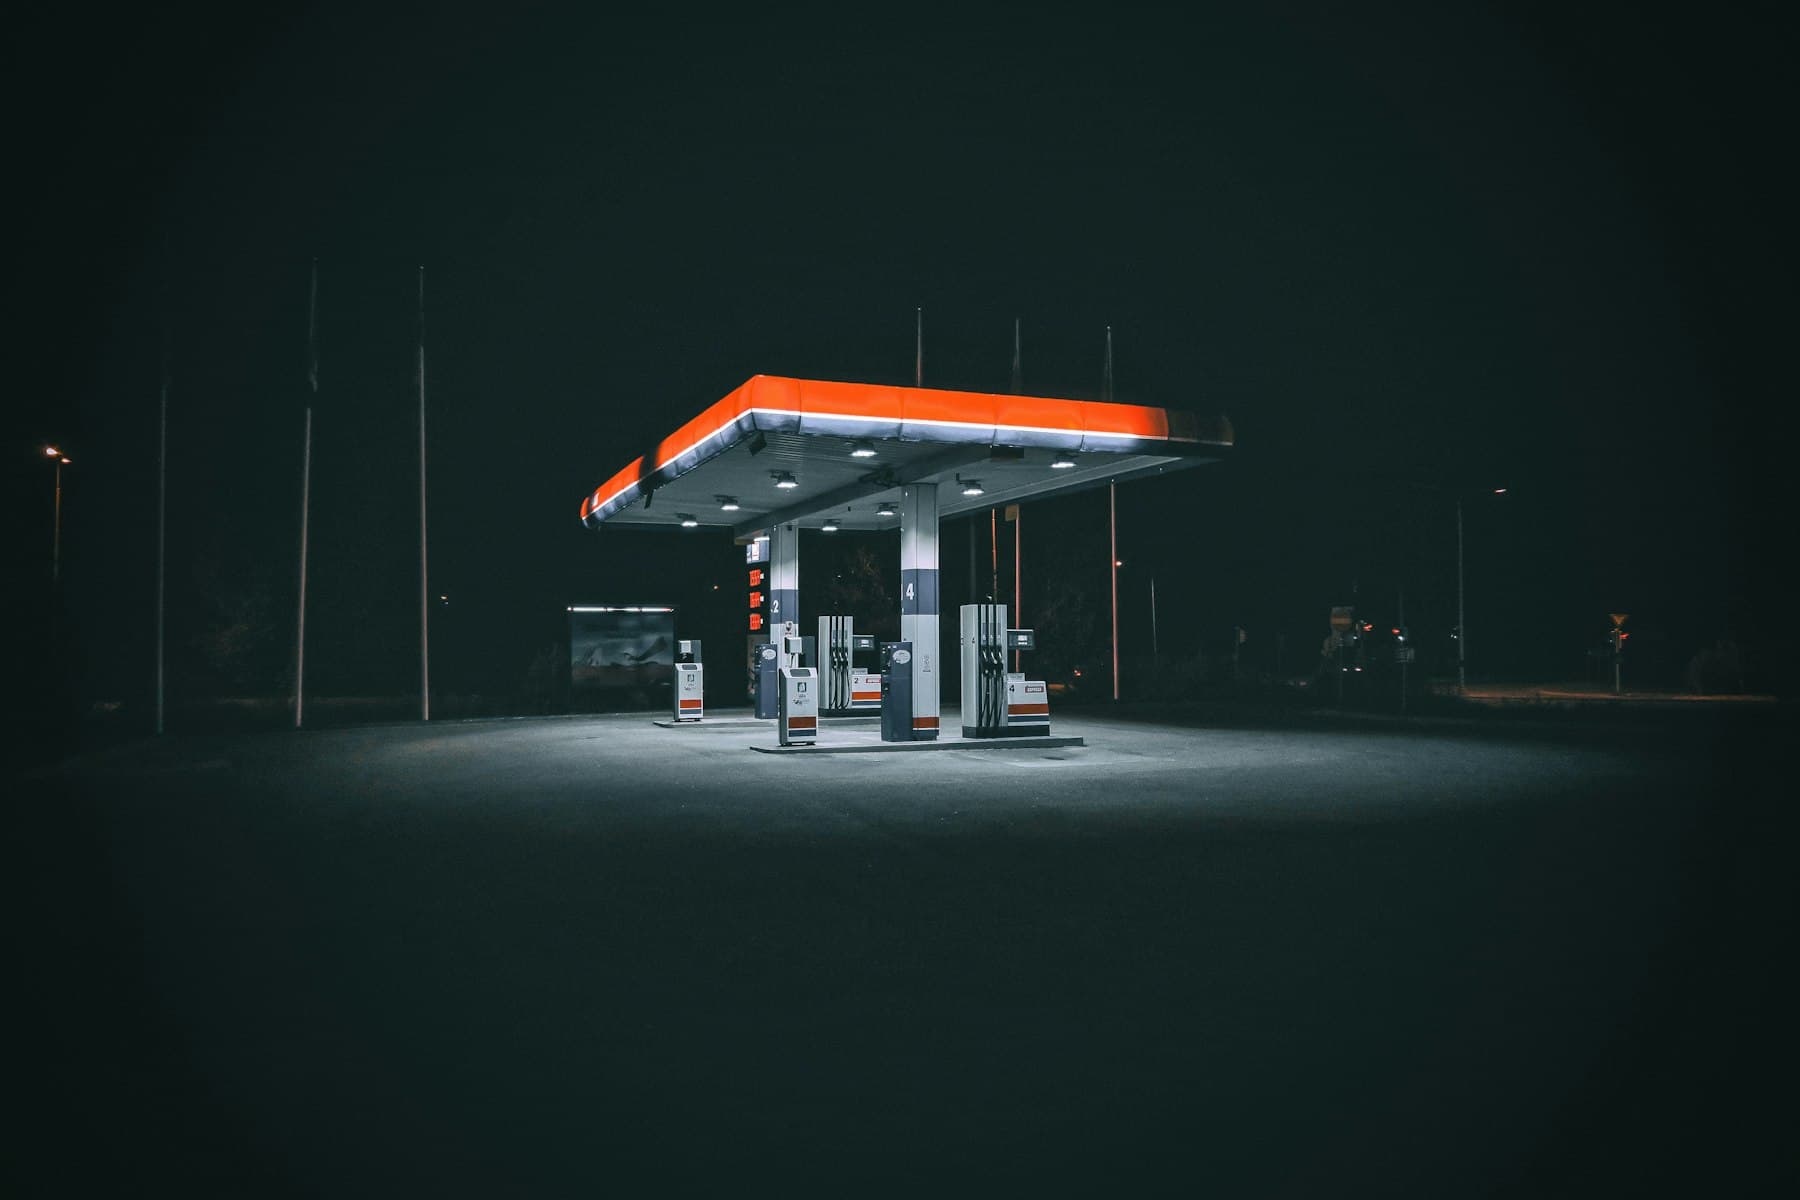
Sell your gas station & convenience store
Fuel centers and convenience stores, corporate or dealer guaranteed, with tanks in the ground and an environmental file. We buy them as they are.
Gas Station & Convenience Store at a glance
- Typical deal size
- $1.5M – $6M
- Lease structure
- Absolute NNN
- Typical term
- 15–20 years
- Escalations
- 5–10% every 5 years
Overview
What gas stations & convenience stores are really worth
Our read
The convenience store is one of the most liquid small-format net lease assets in the country, and one of the most bifurcated. Two stores on opposite corners of the same intersection can trade two hundred basis points apart, and the difference is almost never the building. It is who signed the lease.
A corporate-guaranteed store backed by a national balance sheet is a bond with a canopy. The same building leased to a single-store franchisee is a small business loan secured by real estate. Both are perfectly good assets. They are not the same asset, and pricing them the same way is the most common error in this space.
The second variable is fuel. Tanks in the ground bring environmental liability, regulatory deadlines, and a narrower field of future users — and they also bring the fuel margin that makes the site work. Owners tend to treat the environmental file as a problem to hide. It is more useful as a document to lead with, because the buyers who can actually price it are the ones who will not walk.
Gas stations are the most misunderstood asset in net lease, and the misunderstanding costs sellers money.
On paper they look like any other single-tenant retail property: long lease, absolute NNN, credit tenant, no landlord obligations. In practice they carry two risks that no other retail asset carries — environmental liability that travels with the land, and a re-tenanting universe that is effectively limited to other fuel operators.
That is why cap rates run wider than the lease term would suggest. It is not a discount for a bad asset. It is the market pricing tail risk correctly.
What that means for you: if your site is clean, newer tanks, trust-fund eligible, with a corporate guarantee and real term remaining, you should be pushing hard for the tight end of the range and most brokers will underrepresent what you can get. If your site has a recognized environmental condition or aging single-wall tanks, the conventional buyer pool disappears — and that is precisely the situation we are built for.
Valuation
How we underwrite it
The method
We start with the guarantor, not the brand on the sign. Corporate, franchisee, and dealer guarantees get materially different treatment, and we confirm which one is actually on the lease rather than inferring it from the canopy.
If fuel is present, the tank system gets underwritten as its own line: age, wall construction, leak-detection history, remaining useful life, and state trust fund eligibility. Environmental exposure is priced, not avoided. A site with a known plume and an active remediation plan is often easier for us to value than one with no testing at all.
Trade-area competition is the adjustment sellers dispute most. A newer, larger format nearby genuinely changes the income the site can sustain, and we would rather reflect that in the first number than discover it in diligence and retrade.
If the business conveys with the real estate, inside sales and fuel volume drive a separate valuation on the operating side. Many owners are better off selling the real estate and keeping the business, and we are happy to structure it that way.
What moves the number
- 01Fuel volume and inside sales, if you are selling the business alongside the real estate
- 02Corporate guarantee versus franchisee or dealer guarantee — this is often a 100+ basis point spread
- 03Remaining lease term. Below 10 years, the buyer pool contracts sharply
- 04Environmental status. A clean Phase I is table stakes; a recognized environmental condition changes the transaction entirely
- 05Traffic count and ingress/egress, particularly for a hard corner
- 06Whether fuel is attached, since a c-store with dispensers carries tank liability a dry store does not
- 07Inside sales per square foot, if the business conveys with the real estate
- 08Traffic count, signalized access, and which side of the road the store sits on relative to the commute
- 09Remaining lease term and whether the operator has renewal options at below-market rates
- 10Competition within the trade area, particularly any new build with more fueling positions
Capital markets today
- 10-yr Treasury
- 5.24%
- 4.12% a year ago
- SOFR
- 3.87%
- 4.2% a year ago
- 30-yr mortgage
- 7.28%
- 6.3% a year ago
- CRE loan delinquency
- 1.53%
- 1.57% a year ago
- CRE prices, YoY
- 6.58%
- -2.7% a year ago
Sources: FRED DGS10, 2026-10-01 · FRED SOFR, 2026-10-01 · FRED MORTGAGE30US, 2026-10-01 · FRED DRCRELEXFACBS, 2026-04-01 · FRED COMREPUSQ159N, 2026-01-01
Diligence
What a buyer actually looks at in a gas station & convenience store
- Check 01
Underground storage tanks (USTs)
Age, material, and leak detection history. Single-wall steel tanks installed before the 1988 EPA deadline are a serious problem. Tank age alone can determine whether the site is financeable.
- Check 02
Phase I, and Phase II where indicated
Fueling history makes environmental review non-optional; nearly every gas station transaction requires it. A Phase I that flags a recognized environmental condition triggers a Phase II, and a Phase II that finds contamination triggers a remediation negotiation that can take longer than the rest of the deal combined. Discovering it during a conventional sale is the most common reason those deals collapse.
- Check 03
State trust fund eligibility
Many states operate a UST remediation trust fund. Whether the site is eligible, and whether eligibility survives a transfer, materially affects who bears the cleanup cost. This is frequently the single largest economic term in a gas station deal.
- Check 04
Fuel supply and brand agreement terms
If the site is branded, the supply agreement may carry assignment restrictions, minimum volume commitments, or debranding costs that survive the sale, plus image and equipment upgrade obligations that a change of ownership frequently triggers.
- Check 05
Canopy, dispenser, and equipment age
These are capital items with defined lives. EMV compliance and dispenser age drive capex: a buyer will price a full dispenser replacement into the offer if the equipment is at end of life, and a canopy at end of life is a six-figure adjustment.
- Check 06
Corporate versus dealer guarantee documentation
The entity actually standing behind the lease drives the cap rate more than any other single factor, and the signage often does not match the guarantor.
- Check 07
Inside sales and fuel volume history
If the business conveys, these drive the value. If it does not, they still tell you whether the operator can keep paying the rent.
Backfill risk
What happens if the tenant leaves
The tenant-goes-dark scenario
A convenience store is a purpose-built box on a corner, and that cuts both ways. The good news is that the highest and best use is almost always another convenience store — the traffic count, the curb cuts, and the signalized access that made it work for the last operator make it work for the next one. Brand conversions happen routinely and quickly.
The complication is fuel. A dry convenience store backfills to a wide range of small-format retail. A store with tanks in the ground backfills to a much narrower field, because the next user either wants the fuel business or wants the tanks removed, and removal is expensive.
Where sites genuinely struggle is when a competitor opens nearby with more fueling positions and a larger footprint. Modern c-store formats have grown substantially, and a four-dispenser store across from a sixteen-dispenser travel center is fighting a fight it will not win. That is a trade-area problem, not a building problem, and no amount of capital fixes it.
This is the thing that separates a gas station from any other net lease asset, and it is why cap rates are wider than the lease term alone would suggest. If a fuel tenant goes dark, the re-tenanting universe is not "any retailer" — it is "another fuel operator," because the USTs, canopy, and site plan are purpose-built and the environmental liability travels with the dirt. Converting a former fuel site to non-fuel retail means tank removal, potential remediation, and often a full site redevelopment. A buyer is underwriting that tail risk whether they say so or not. Sites with newer double-walled tank systems, clean environmental history, and trust fund eligibility trade meaningfully tighter for exactly this reason.
Why this matters to you
Every buyer prices the tenant-goes-dark scenario, whether or not they say so out loud. It is the largest hidden input into the cap rate you get offered.
Understanding it before you go to market is the difference between negotiating and being negotiated with.
Who sells to us
Situations we see most often
- Dealer or jobber consolidating a portfolio and exiting non-core sites
- Operator who owns the real estate and wants to convert to a sale-leaseback to fund expansion
- Estate or family partnership where the operating business has been sold and the real estate remains
- Site with a decommissioned or aging UST system that the owner does not want to remediate
- Redevelopment play where the fuel use is no longer the highest and best use of the corner
- Operator retiring and selling the real estate separately from the business
- Franchisee exiting after a brand conversion requirement they do not want to fund
- Owner facing a tank replacement or upgrade deadline
- Portfolio owner pruning single locations from a multi-site holding
- Lease running short and the operator undecided on renewal
Buy box
What we buy
- 01Corporate or strong franchisee guarantee preferred, but we buy dark sites
- 02$1.5M – $6M, with capacity for portfolios above that
- 03We will take on environmental. A recognized environmental condition is not a dealbreaker for us — it is a pricing conversation
- 04Nationwide, with concentration in the Sun Belt
- 05Corporate and dealer-guaranteed sites, $1M to $6M
- 06With or without fuel
- 07Environmental history welcome — including active remediation
- 08Short remaining term and vacant boxes considered
Process
How selling to Dizposition works
Day 0
01Send us the property
Address, asset type, and the lease if there is one. That is enough for us to start.
- 02
We underwrite it
Our underwriting runs the income against current market pricing and the cost of capital. No lowball anchor.
10 minutes
03You get a firm offer
In 10 minutes, with the math shown. You will know exactly how we got there.
As fast as 30 days
04Close on your timeline
As fast as 30 days, or as slow as you need. We are the principal, so the date is yours.
FAQ
Selling a gas station & convenience store
Can I sell a gas station with contaminated soil?
Yes, and we buy them regularly. Contamination is a pricing and structuring question, not a dealbreaker. What matters is the scope, whether the site is eligible for a state trust fund, and who takes the go-forward remediation obligation. Most conventional buyers walk from these; we do not.
Do I have to sell the fuel business along with the real estate?
No. We buy the real estate on its own, and many of our sellers keep operating under a sale-leaseback. If you want to exit the business entirely we can structure that too, but the two are separable.
Why are gas station cap rates wider than other net lease retail?
Backfill risk and environmental tail risk. If a fuel tenant goes dark, the practical re-tenanting universe is other fuel operators, because the tanks and site plan are purpose-built. Buyers price that in.
What if my tanks are old?
Tank age is one of the first things we underwrite. Single-wall steel systems predating the 1988 EPA standards are a real issue and will affect price, but they do not stop us from transacting.
My store is dealer-guaranteed, not corporate. How much does that cost me?
It widens the cap rate, sometimes considerably, because the credit behind the lease is a small business rather than a national balance sheet. It does not make the property unsellable. We underwrite the operator's actual performance rather than only the guarantee, which is usually a better outcome for you than a conventional buyer's blanket discount.
I have underground tanks. Does that make this harder?
It makes it harder to sell conventionally and easier to sell to us. Tank age, construction, and leak history all get priced. State trust fund eligibility matters a great deal and is worth confirming before you market the site.
Can I sell the real estate and keep running the store?
Yes — that is a sale-leaseback and it is one of the most common structures in this asset class. You get the capital out of the building and stay in operation on a long-term lease.
A large travel center just opened a mile away. Is my site still worth anything?
Yes, but the trade area has changed and the number will reflect that. Tell us early rather than letting us find it — we would rather price it correctly the first time than retrade you later.
How long does it take to sell a commercial property to Dizposition?
You get a firm written offer within 10 minutes of sending us the property. If you accept, you can close in as little as 30 days — most of that is title work and your own timeline. There is no listing period, no marketing, and no waiting on a buyer's financing contingency.
Can I sell my property as-is?
Yes. We are the buyer, so there is no lender requiring repairs and no inspection contingency to renegotiate against you. Deferred maintenance, a failing roof, an aging tank system — we price it into the offer rather than asking you to fix it first.
Can I sell with a tenant in place?
Yes, and in most cases a tenant makes the property more valuable to us, not less. We will ask for the lease, a rent roll, and any estoppel certificates. You do not need to deliver the property vacant.
What if my lease is short-term or about to expire?
Short remaining term is one of the main reasons owners come to us. A conventional buyer needs lease term to get financing, which is why short-dated assets sit on the market. We underwrite the real estate and the backfill prospects rather than the remaining term alone.
What if the property is vacant?
We buy vacant assets. Pricing shifts from an income approach to what the building and land are worth to the next user, which is a different calculation — but it is one we do routinely rather than one that disqualifies the property.
Do I need a broker to sell to you?
No. We buy directly, and there is no commission because there is nothing to market. If you already have a broker, we will pay them. Selling without one saves the commission, but you should understand you are also giving up price discovery — a broker's job is to find out whether someone will pay more than we will.
What documents do I need to get an offer?
The address and the lease are enough to start. To finalize, we will want the rent roll, the last two years of operating statements, the title commitment, any existing survey, and any environmental reports you already have. You do not need an appraisal or a broker package.
How do you determine your offer?
We underwrite in-place income against what the space would re-lease for, adjust for capital needs and any environmental tail, and apply a cap rate supported by comparable transactions. We show you the inputs. If you disagree with an assumption, we would rather argue about the assumption than about the number.
What are typical seller closing costs?
Title and escrow fees, any transfer or recording tax owed in your state, prorated property taxes, and payoff of any existing debt. Because we are the buyer, there is no commission and no marketing cost. Transfer tax varies significantly by state and is often the largest single line.
Will I owe capital gains tax when I sell?
Usually yes, on the gain above your adjusted basis, and depreciation recapture is taxed separately from appreciation. State treatment varies. This is a question for your CPA before you sign, not after — the structure of the sale can change the answer.
Can I do a 1031 exchange?
Yes. A 1031 exchange lets you defer federal capital gains by reinvesting in like-kind property, subject to a 45-day identification window and a 180-day closing window from the date you sell. You must have a qualified intermediary in place before closing — it cannot be arranged afterward. Most states conform to federal treatment, but a few do not.
Can I sell if I am behind on payments or facing foreclosure?
Yes, and speed is the reason to move early rather than late. We can close on a defined date, which is what a lender or a receiver generally needs to see. Send us the payoff figure and any notices you have received.
Can I sell a property I inherited or that is in probate?
Yes. Probate sales take longer because the court timeline governs, not ours, and multiple heirs need to agree on the price before anything can close. We are used to working around both. Inherited property also generally receives a stepped-up basis, which can change the tax math substantially.
Is there any cost or obligation to get an offer?
None. There is no fee, no listing agreement, and no obligation to accept. If our number does not work for you, you keep the underwriting we showed you and we part ways.
Markets
Top markets we buy gas stations & convenience stores in
Where the inventory is
96,002 U.S. establishments · Gasoline stations with convenience stores
- 01Sell a gas station & convenience store in Texas9,720
- 02Sell a gas station & convenience store in California6,766
- 03Sell a gas station & convenience store in Florida5,539
- 04Sell a gas station & convenience store in Georgia4,644
- 05Sell a gas station & convenience store in North Carolina4,001
- 06Sell a gas station & convenience store in New York3,560
- 07Sell a gas station & convenience store in Ohio3,468
- 08Sell a gas station & convenience store in Illinois3,407
- 09Sell a gas station & convenience store in Tennessee3,213
- 10Sell a gas station & convenience store in Michigan3,199
Sources: U.S. Census Bureau, County Business Patterns, NAICS 447110, 2023
Browse by state
50 state markets
- Arizona
- Texas
- Florida
- Alabama
- Alaska
- Arkansas
- California
- Colorado
- Connecticut
- Delaware
- Georgia
- Hawaii
- Idaho
- Illinois
- Indiana
- Iowa
- Kansas
- Kentucky
- Louisiana
- Maine
- Maryland
- Massachusetts
- Michigan
- Minnesota
- Mississippi
- Missouri
- Montana
- Nebraska
- Nevada
- New Hampshire
- New Jersey
- New Mexico
- New York
- North Carolina
- North Dakota
- Ohio
- Oklahoma
- Oregon
- Pennsylvania
- Rhode Island
- South Carolina
- South Dakota
- Tennessee
- Utah
- Vermont
- Virginia
- Washington
- West Virginia
- Wisconsin
- Wyoming
Other property types
- Warehouses & Distribution Facilities
- Car Washes
- Storage Facilities
- Industrial Outdoor Storage Facilities
- Manufacturing & Logistics Facilities
- Office Buildings
- Medical Offices
- Shopping Centers
- Hotels & Motels
- Marinas
- Multifamily Properties
- Assisted Living Facilities
- RV & Mobile Home Parks
- Parking Garages & Lots
- Campgrounds
- Billboards
- Cell Towers
- Churches
- Funeral Homes
- Commercial Land
- Farms & Ranches
- Resorts & Retreats
- Auto Collision & Repair Shops
- Auto Parts Stores
- Oil Change & Lube Centers
- Truck Stops
- Grocery Stores
- Drive-Thru & Casual Dining Buildings
- Coffee Shops
- Liquor Stores
- Pharmacies
- Dispensaries
- Urgent Care Centers
- Veterinary Clinics
- Dialysis Centers
- Dollar Stores
- Cell Phone Stores
- Early Education Centers
- Private & Charter Schools
- Bank Branches
- Movie Theatres
- Pawn Shops & Check Cashing Stores
- Data Centers & Battery Farms
- Post Offices
- Government Buildings
- Auto Dealerships
- EV Charging Stations
- Hospitals & Surgery Centers
- Gyms & Fitness Centers
10-minute offer
Ready to sell your gas station & convenience store?
Send us the property and the lease. You'll have a firm offer, with the math shown, in 10 minutes.